Let me talk a little about what is not working so well in my Daedalus income portfolio this year (and probably can include last year if we are pretty strict about it).
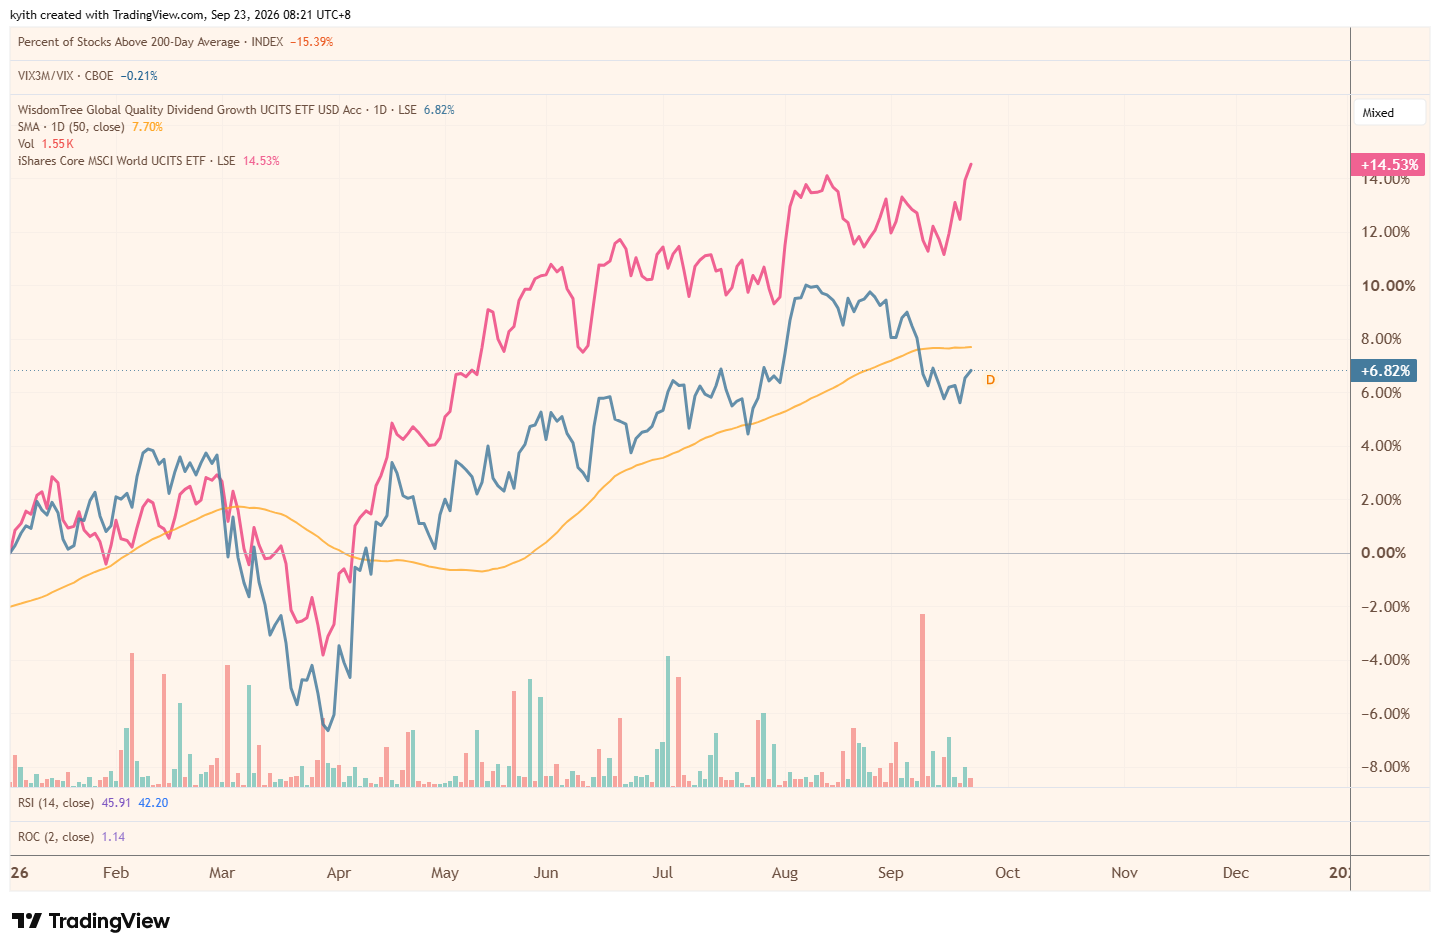
The WisdomTree Global Quality Dividend Growth UCITS ETF, ticker GGRA makes up 7% of my overall portfolio. In absolute terms its about $135k. GGRA, together with AVGS, IFSW, and JPGL forms the Large Cap, Mid Cap part of my developed market allocation.
Year to date its doing 6.8%. The MSCI World, if we use SWDA as a proxy is doing 14.5% at this point. If I go back to the start of 2025, the performance difference would be 24% to MSCI World’s 28%.

I have to remind myself what I invest in GGRA for. It, together with AVGS, IFSW, JPGL gives me a developed market regional equity exposure. I subscribed to the investment philosophy that if we screen for companies that ranked high in medium-term estimated earnings growth, high 3-year average ROA or ROE, you end up with companies who is able to growth their free cash flow and subsequently dividend per share better.
If we systematically invest in a group of these companies, then periodically curate them passively, the returns should be decent.
Decent to achieve my financial objective, which is to provide income. This is before beating the index. Over time, it should do decently versus the index as well.
As a long time bottoms-up fundamental investor, I can understand the fundamentals of this strategy.
In a way, this sub-segment of my developed world multifactor slice is the high quality or profitability segment.
Now… returns are ultimately driven by the underlying basket of securities.
And a basket of high quality securities have done very well for the past 15 years. If you invest in quality, you are likely to end up with some information technology firms or healthcare companies. This year, you kind of know what has happen to those information technology companies with recurring seats-based income. They got demolished and of course would not have done well. The strategy won’t happen to own segments of the AI-beneficiary.
In all strategies there will be periods where you squirm and periods where you are very appreciative for. The value investors have a great surprise when Micron turn out to be a great winner.
GGRA is not meant to invest in AI or non-AI companies. Information technology companies or other companies. Its meant to screen for high quality companies that will pay and raise dividends.
Quality or profitability are some of the more “smoothed” factors. This means you are likely to see the factor premiums show up more consistently. In comparison, value premiums are likely to come in spurts.
I don’t think you can see it always as “not working out”. Or ask the question: “Kyith, how long must we wait until it starts working?”
If I were to give an answer, its 20 years. But we don’t have so many 20 years to correct this “mistake” if it doesn’t work out.
And so that is the risk. Remember you can also invest in an index, and for any kind of factor to end up outperforming the index. Then how would you feel after 20 years?
There is always a risk and therefore a premium potential. If there is no risk… then where does the return come from.
I visualize if… GGRA is 100% of Daedalus and it has done 6.8% this year how would I feel?
Of course if I compare against the MSCI World, it would not feel good. If you compare against the Singapore index or the banks it will suck more.
Comparison is the teeth of joy but I felt that we have to balance them up with some sensibilities as a long term investor. There will surely be days when those index suck more.
And then… what do you want to do about it? Do you want to sell every time something is not working? Buy what is working, then keep selling what is not working, hoping from one thing to another for the next 40 years?
You might feel that its a good way of life. Perhaps you would feel that there is this holy grail that Kyith fail to find that always works in up markets, down markets, sideways market.
Well I don’t think I want to live my next 30 years keep meddling. The premiums or the non-premiums in research is not a 1-year or 5-year thingy.

I should also be clear that not every quality or profitability like strategy is doing this. I have added the iShares Edge MSCI World Quality Factor UCITS ETF (IWQU) in purple. You can see it is doing decently well.
We can screen for quality in different ways. What is considered quality to you or me can be rather different.
Would I change this slice into something else?
It is possible if I :
- Understood and agree with the drivers and the way the fund screens for the basket of securities.
- It is systematic and passive.
- It is under a UCITS structure.
- It is available in IBKR.

Kyith is the Owner and Sole Writer behind Investment Moats. Readers tune in to Investment Moats to learn and build stronger, firmer wealth foundations, how to have a Passive investment strategy, know more about investing in REITs and the nuts and bolts of Active Investing.
Readers also follow Kyith to learn how to plan well for Financial Security and Financial Independence.
Kyith worked as an IT operations engineer from 2004 to 2019. Currently, he works as a Senior Solutions Specialist in Fee-only Wealth Advisory Firm Providend. All opinions on Investment Moats are his own and does not represent the views of Providend.
You can view Kyith’s current portfolio here, which uses his Free Google Stock Portfolio Tracker.
His investment broker of choice is Interactive Brokers, which allows him to invest in securities from different exchanges all over the world, at very low commission rates, without custodian fees, near spot currency rates.
You can read more about Kyith here.