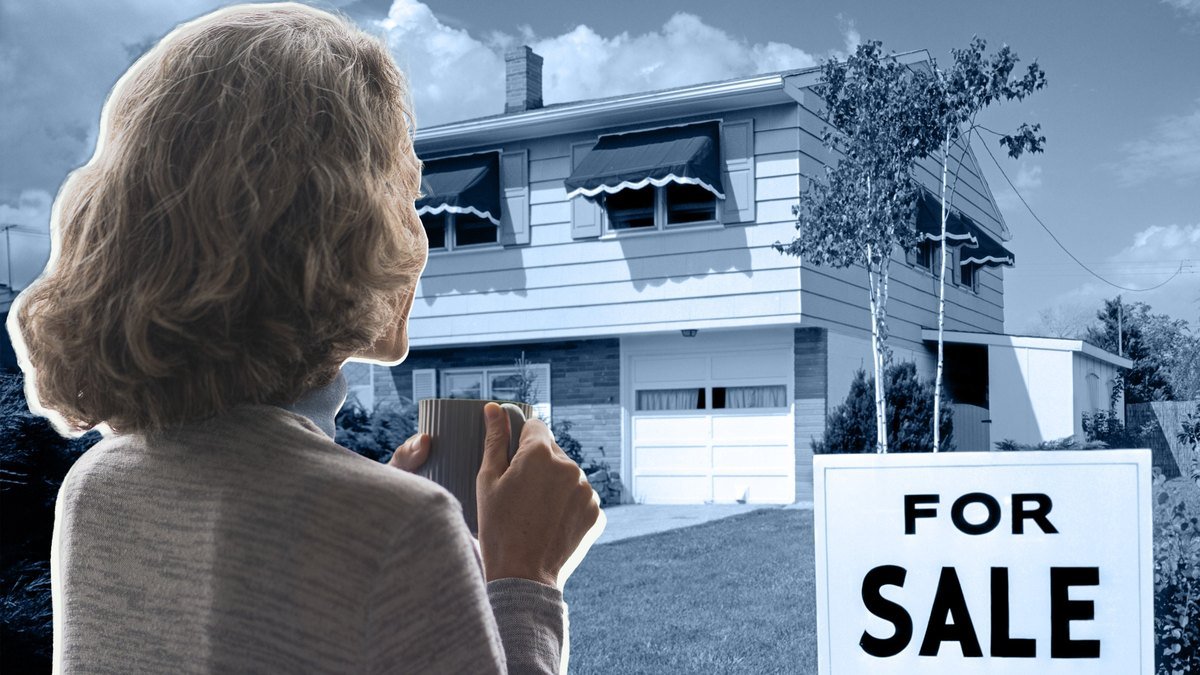
The “silver tsunami” may finally reach America’s shores, bringing enough homes to ease its long-running inventory shortage and expose an entirely new problem in its place.
Between 2026 and 2036, an estimated 13.9 million homes currently occupied by baby boomers and the Silent Generation will be released from older owner-occupancy, according to the Generational Housing Succession report from Realtor.com® released on Monday.
The annual pace is projected to rise from roughly 1.27 million homes in 2027 to 1.52 million by 2036.
And if just 45% of the homes projected to be released in 2027 became for-sale listings, that alone would be enough to restore annual listings to pre-pandemic levels, all else being equal, the report found.
It’s good news for the multitudes of house hunters who have spent the past few years on the sidelines as scarce listings limited their options and helped keep prices elevated. But restoring the number of homes for sale does not necessarily restore a balanced—or affordable—market.
“We believe the softness will be real, though its effects will be uneven across segments and markets, not a uniform, nationwide correction,” Jiayi Xu, senior economist at Realtor.com, writes in the report.
The problem is that the homes coming back don’t neatly match the parts of the market where buyers face the greatest scarcity. And the handoff is arriving just as demographic growth in housing demand is projected to slow.
After years of a market defined by broad scarcity and shortage, the coming flood could create a new kind of divide: too few buyers for some homes, and too few homes for the others.
The homes coming back don’t match the shortage buyers feel
Only about 380,000 of the homes projected to be released will have two or fewer bedrooms, the report found. Nearly three-quarters will be three- or four-bedroom family homes, with millions more containing five bedrooms or more.
Relative to the size of today’s market, the divide is even sharper. Average annual releases amount to only about 3.2% of recent starter-home listings, compared with 24.7% of family-home listings and 67.2% of large-home listings.
Put more simply, the silver tsunami is poised to add the least supply where buyers are already under the greatest pressure—and the most where demand may face a much bigger test.
A separate May analysis from Realtor.com and the National Association of Realtors® found that homes affordable to a household earning about $75,000 represented just 23% of listings, roughly half the share expected in a balanced market.
The two studies measure the market differently—one by bedroom count, the other by price—but together they point to the same mismatch: More choice helps only if it matches demand.
Older buyers could keep competition for smaller homes elevated, too.
Using American Community Survey households that moved within the previous 12 months as a proxy for recent buyers, Xu found that roughly 30% of buyers of starter-sized homes were 60 or older.
“Around 30% of buyers of starter homes are aged 60 and above, suggesting older buyers, whether downsizers or late-life first-time buyers, may compete meaningfully with younger, first-time buyers for this segment,” Xu says.
So while aging households will bring new supply to the market, they may also bring buyers, potentially redirecting demand toward smaller homes even as other older owners release larger ones.
More family-home inventory could eventually relieve that pressure indirectly. Existing starter-home owners may find it easier to trade up, freeing their previous homes for new buyers.
But Xu cautions that the chain will take time.
“It is important to note that this ‘free-up’ mechanism is a secondary channel, and it may take longer to materialize,” she says. “The primary solution to the starter-home shortage remains more new construction.”
After years of too little supply, could demand become the next problem?
The same demographic shift beginning to loosen housing supply could also weaken the demand needed to absorb it.
The number of U.S. households is projected to grow by 8.6 million between 2025 and 2035, according to a September analysis from Harvard’s Joint Center for Housing Studies—far slower than over the preceding decade.
The reason is largely demographic. As the baby boom generation ages, losses of older households are accelerating while household formation among younger adults is also expected to slow.
And while the country will continue adding households, Harvard finds that the collision of these demographic forces could eventually cool housing demand.
That raises a question the housing market hasn’t had to answer for years: Will there be enough buyers to sustain demand? But household growth alone can’t answer it—the macro conditions of the market will also play a decisive role.
Higher mortgage rates, for example, can shrink the buyer pool without making homes more affordable for those who remain.
“First-time homebuyers themselves are rate-sensitive, so any net benefit from reduced competition would need to outweigh the direct cost of financing at a higher rate, which makes the mechanism unlikely to deliver a clear win in reality,” Xu says.
The condition of the homes being released can narrow that pool further.
“A $700,000 home that needs $100,000 in improvement doesn’t necessarily solve the affordability issue for most first-time buyers, but it does help some,” says Lisa Harris, an associate at Re/Max Center in Braselton, GA.
The mismatch will be local
Whether that imbalance becomes large enough to move prices will depend on where it occurs, and there’s already some evidence that certain markets are more exposed than others.
April research from the National Association of Home Builders identified markets such as Pittsburgh, Buffalo, NY, and Rochester, NY—where older populations coincide with slower population growth—as at risk for housing turnover to outrun new demand.
Other metros have stronger population growth or more pent-up demand capable of absorbing the homes older owners release.
The new home-type findings from Realtor.com add another wrinkle: A market’s ability to absorb that turnover will depend not just on how many homes become available, but also on whether there are enough local buyers who want—and can afford—those particular homes.
That means demand may start to mean something much more specific in the years ahead: enough buyers, in the right market, for the right type of home, at the right price.
In Las Vegas, real estate agent Bob Little says he is already seeing some of those forces at work.
“I don’t think baby boomer turnover by itself is going to dramatically change affordability,” he says. “Interest rates and overall buyer demand are still much bigger factors in our market.”
Xu says the next evidence will come from watching whether relief higher up the housing ladder begins spreading elsewhere.
“What we’ll be watching for instead is whether family and large homes continue to see real relief as projected, and whether that relief stays contained to those segments or eventually spill over to ease pressure on entry-level buyers as well,” she says.