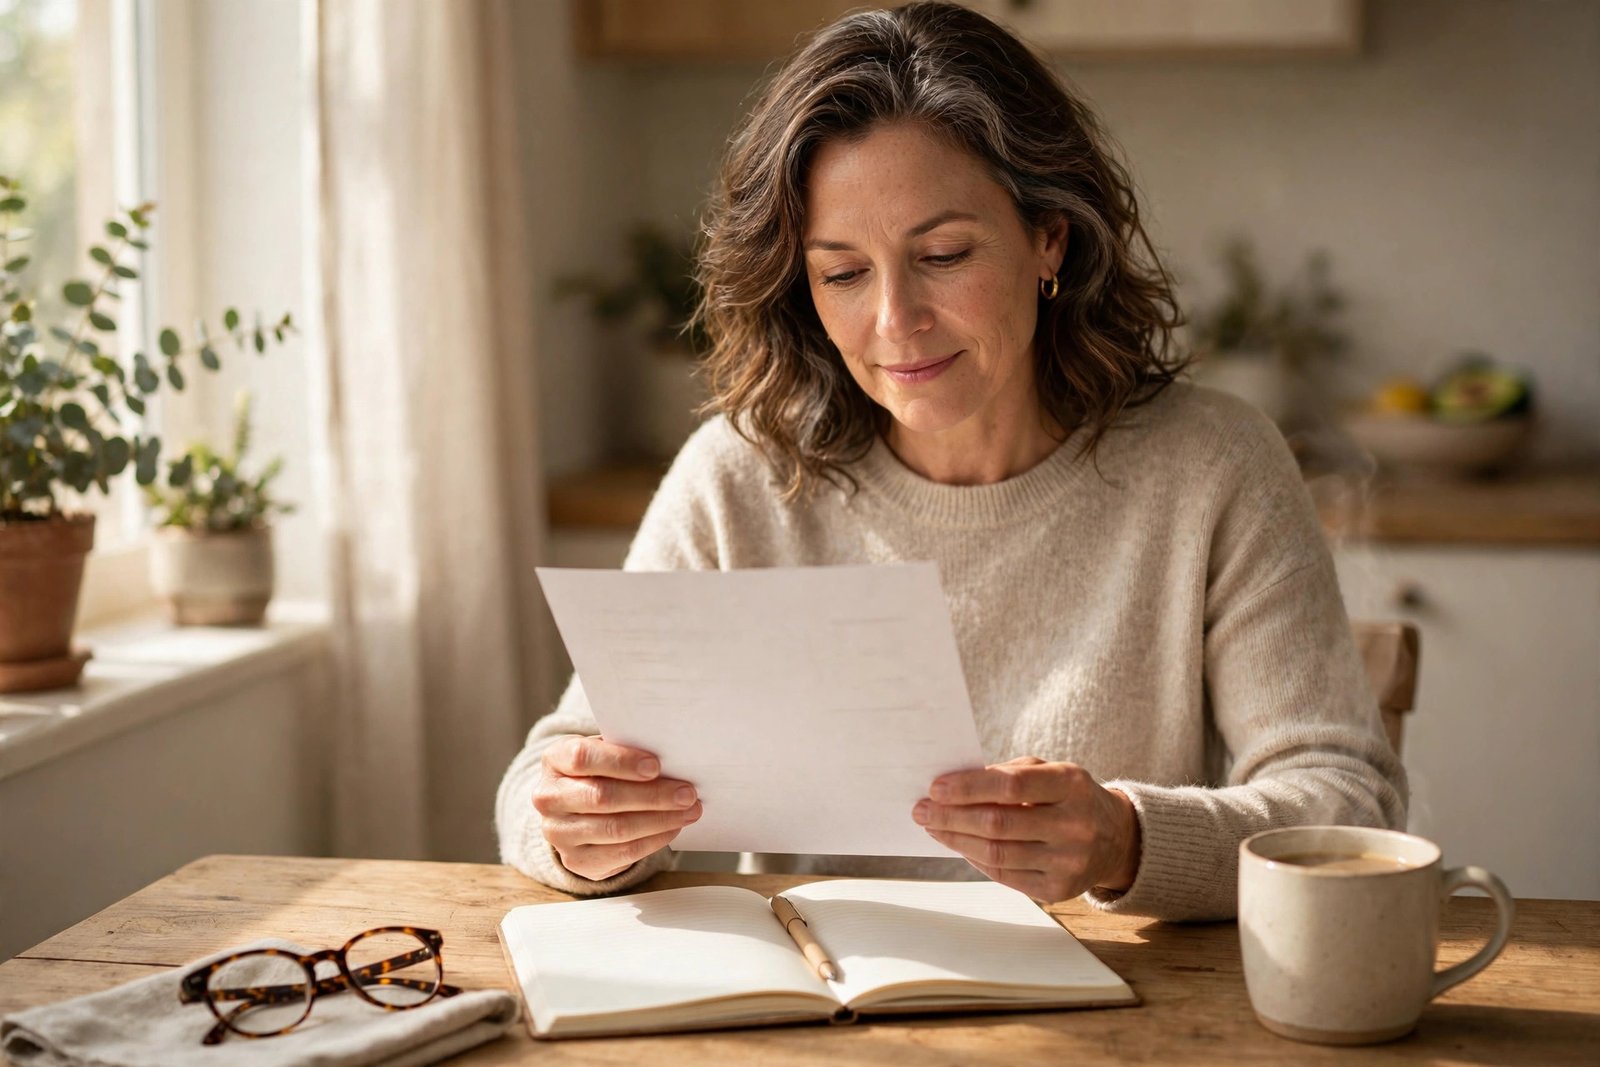
A few months ago I finally did the thing I’d been avoiding: I opened my retirement account and actually looked at the balance. Not a quick glance — a real look. And my first thought was not a kind one. It was something like, “Well, that’s not nearly enough, and I’m running out of time.”
If you’ve ever had that same sinking feeling, I want you to know something I had to learn the hard way: that feeling is not a fact. It’s a starting point. And starting late is still starting.
First, I stopped doing the shame math
For years, every article I read about retirement seemed written for someone who started saving at 22 and never missed a beat. That was never me. Life happened — bills, moves, raising a family, jobs that didn’t offer a 401(k). Comparing my balance to some “you should have this much by 40” chart only made me want to close the tab and pretend the problem didn’t exist.
So I stopped. I stopped measuring myself against a timeline I didn’t get to choose, and I started measuring against one question: what can I do from here?
Then I found out where I actually stand
Before I could make a plan, I needed a number — not a scary one, just an honest one. I added up what I have saved for retirement, checked what my employer plan (if you have one) actually offers, and wrote down roughly when I’d like to stop working full-time.
It took about twenty minutes, and it was nowhere near as bad as the version I’d been carrying around in my head. Vague worry is always worse than a real number. If you want a quick, judgment-free way to check where you stand, I built a free tool for exactly this moment: Am I Behind? — it walks you through a simple check in a couple of minutes, no sign-up, nothing saved.
The three levers I can actually pull
Once I knew my number, the plan got simple. There are really only three levers, and I didn’t have to pull all of them at once:
Save a little more. I bumped my contribution by just a few percent — small enough that I barely noticed it in my paycheck, big enough that it adds up over years. If your job offers a 401(k) match, grabbing the full match is the first move; it’s the closest thing to free money that exists.
Earn a little more — on purpose. This is the one nobody talks about in retirement articles, but it’s the lever with the most room in it. A small side income, even a few hundred dollars a month, aimed straight at retirement savings, can change the math more than skipping lattes ever will.
Spend a little less — in one place. Not a whole frugal overhaul. I picked one category, just one, and trimmed it. One change is a plan. Ten changes is a punishment, and punishments don’t last.
Don’t forget the catch-up rules
Here’s something I genuinely didn’t know until recently: if you’re 50 or older, the IRS lets you put extra money into your 401(k) and IRA beyond the regular limits. They’re called catch-up contributions, and they exist precisely for people like us who are starting later. Check with your plan or a tax professional for the current limits — they change from year to year — but knowing the option exists took a lot of pressure off me.
Automate it, then stop thinking about it
The best decision I made was making the whole thing automatic. The money moves on payday, before I can talk myself out of it. I check in once a month, not once a day. Retirement savings is a slow cooker, not a microwave — it works best when you set it and let it do its thing.
Here’s what I’d do this week
If you’re where I was a few months ago, here’s the whole plan in one week: today, find your number. Tomorrow, check whether you’re getting your full employer match. This weekend, bump your contribution by a small amount — even 1% counts. And if you want a little structure around the money side of your life, the free tools and guides at my shop, SoRavelyn are there when you need them.
You’re not behind. You’re beginning. And beginning now beats beginning “someday” every single time.